Friday, April 22, 2022

Inflation, Employment, Recession, and Housing: Where the Economy Is Now, and Where It Is and Isn’t Heading

What’s happening with our financial system?  We’ve heard a lot about inflation, but there’s more on other aspects as well.  All from the last month – let’s go!

The Washington Post’s Breaking News told us on April 12th that “Prices climbed 8.5% in the year ending in March, amid growing fears that inflation will cause a broad economic slowdown.”  This is a fresh 41-year high, but at least the rate seems to be topping off, and seems unlikely to reach even 10%.  With booming weaker-Covid demand, the Ukraine war, Chinese pandemic problems, nagging supply chain issues, and even another Japanese earthquake it won’t go away soon, though, but will start falling this summer, such general optimism supported by Paul Krugman in the March 24th New York Times “How High Inflation Will Come Down.”  However, if you are thinking about buying a vehicle, you might as well do it soon, as per Jeanne Smialek in the April 10th New York Times, we’re looking at “Few Cars, Lots of Customers:  Why Autos Are an Inflation Risk,” with one dealer saying “If I could get 100 Toyotas today, I would sell 100 Toyotas today,” and their supply-demand situation calling for them to fetch maximum prices indefinitely.  Emma Goldberg told us that “With Inflation, Workers Are Facing Return-to-Office Sticker Shock” (The New York Times, April 20th), meaning there is a new disadvantage of not being able to work from home, as gas, coffee, and lunch food all cost more and the differences can add up quickly.

Again in the Times, Andrew Ross Sorkin et al. posed the question “Is U.S. employment at Its Peak?” on April 1st.  That’s good to ask, with official joblessness under 4% and still dropping, the count of open job advertisements of variable quality reaching all-time highs, and the American Job Shortage Number (AJSN) within one or two good employment reports of reaching a decade-plus-long latent-demand low.  The economy is still “two million jobs short of its prepandemic peak,” but two years of intensified efficiency and automation, along with the usual globalization, account for much of that, and national population growth, about one-third of that time’s level, has not been able to help.  We may soon drop through unemployment’s 3% and the AJSN’s 16 million, and if we do we will know the March report was not the high mark.

You may have heard of the Big Mac Index, which uses international prices for that sandwich to assess whether their currencies are overvalued or undervalued relative to others, but how about the men’s underwear index?  I learned about that in “Is a recession coming?  Alan Greenspan days the answer is in men’s underwear” (Nicole Goodkind, CNN Business, March 26th).  The former Federal Reserve chair supports the idea that, since other people rarely see other men’s shorts and their sales are “usually stable,” when they decline “that means that men are so pinched that they are deciding not to replace underpants.”  The piece contained no data on this metric, but also mentioned the “skyscraper index,” based on the notion that “an increase in very tall buildings happens as we’re approaching a bust,” and the “lipstick index,” trading on the thought that cosmetics function as economic inferior goods, as in hard times “women replace more expensive purchases with small pick-me-ups.”  None of these things are comprehensive, of course, but all seem worthwhile.  As for a recession soon, since neither employment nor consumer demand seem at all likely to crash, and cited precedents were all without pandemics, there’s little reason for a gloomy forecast.

“Is the U.S. already in a housing bubble?”  Brock Sumas asked this in Fox Business on April 20th.  Real estate prices are not a “paradox,” as Krugman has put it, but only a combination of burgeoning demand offset somewhat by higher mortgage rates.  As for a “bubble,” defined by a quoted economist as “an unsustainable period of house price growth generated by artificial demand, such as loose underwriting or speculative demand” – and we have seen both this century – this same source opined that higher prices are now “supported by the fundamentals and characterized by a shortage of supply relative to demand.”  Suras said that the presence of a bubble was “open to debate,” and there surely will be some localized price decreases, but to me it looks nonexistent.

We end with another, more comprehensive query: “Is America’s Economy Entering a New Normal?” (Jeanna Smialek, March 24th, The New York Times).  With Covid-19 still in progress, it seems too soon to answer anything this long-range, or be surprised that “economists have spent the past two years expecting many of the pandemic-era trends to prove temporary, but that has not yet been the case.”  We also need to understand that we will have gone through a significant amount of time, with as before change in some areas being accelerated, when American new case numbers drop below 1,000 per day and deaths reach double figures or less.  Other changes, such as more remote work, have been cyclical, and other factors, such as pooling up of money and most work acceptors not being technically unemployed, long predate the first coronavirus case.  Six to twelve months from now, an aggressive if anything estimate on the pandemic’s fading, is as soon as we should even consider what will happen long-term with our economy – and, even then, we will be unsure.  That may not be encouraging, but it is realistic – and realism is what we need.

Friday, April 8, 2022

Offices vs. Remote: Perceptions and Changes Keep Coming In, And Will Continue

One of the great employment-related 2020s issues is whether to work, or allow work, from an office.  As I have written, that’s really a 30-year-old problem, pushed to the forefront by and evolving faster because of the pandemic.  What has been written about it in recent months?

The oldest here is “One Size Doesn’t Fit All:  Employees’ Needs Are Changing Work Spaces” by Jane L. Levere in the October 19th New York Times.  The lead example was “M. Moser’s 10,000-square-foot Manhattan headquarters,” “designed in 2018 and revamped in 2020” to be more “flexible,” in other words without personal office space.  An architectural firm is advocating that workers arrive in an “anti-anxiety office entry” with “breathable and easily navigable spaces” to “choreograph the arrival experience to reduce crowding.”  Whew.  Perhaps this stuff will work, but more likely it’s just another set of business fads, to be swept away when businesses rediscover more efficient space design.

Is it true that “Remote Work Is Failing Young Employees” (Anne Helen Petersen and Charlie Warzel, The New York Times, November 22nd)?  It’s about how workers’ online instructions for getting acclimated to their jobs, right or wrong, don’t work as well as getting help in person, summarized by an interviewed new hire who said “I was shocked at how all the skills I had learned on how to navigate this type of environment in person evaporated remotely.”  Another claimed he “found it nearly impossible to socialize with colleagues,” perhaps caused by “well-intentioned but frazzled managers” with little “support or practice in remotely onboarding employees.”  A real gap, which may require working from home to be preceded by at least a week or two with others.

Strange times bring a strange vocabulary, and to keep you up at least partially, we got, from the same author, date, and publication as the previous, “The New Language of the Office, From Al Desko Dining to Zoombies.”  The two expressions in the title came along with “bookcase credibility” (specific titles on display during video calls); “commuter’s delight” (treats brought into the office for those unlucky enough to be there); “polywork,” or non-company financial projects consuming remote workers’ office-hours effort; and “synchronous time,” reflecting more difficulty in connecting simultaneously.  As “office lingo signals affiliation with an in-group,” these terms, and others coming along, are not only valuable but constructive.

“Is working remotely an option for the long haul?” (Paul Davidson, USA Today and published in the Times Herald-Record, December 27th)?  This piece, mainly a primer on then-current statuses which change month by month, doesn’t answer that.  People saying yes and no could write dueling books – a debate would be too short – and we could decide.  My take is “it depends in the individual employee and their job responsibilities,” but we’re hardly likely to decide quickly.  One possible response, by Amy Sinatra Ayres from and in the same publications and appearing January 16th, titled “Experts:  Virtual work is here to stay,” emphasized employee preferences while admitting that “finding the right combination of in-person and virtual work will take creativity and experimentation” and that “nobody knows the answer.”  And most businesses will understand even less when the pendulum swings back yet again.

Another issue primarily but not exclusively with working from home is “What We Lose When Work Gets Too Casual” (Elizabeth Spiers, The New York Times, February 7th).  So, “which parts of office culture were obliterated by Covid and need to be restored because they benefit workers more than they benefit corporations?”  For Spiers, that could include “fixed start and stop times,” “managerial hierarchies with clear pathways for advancement,” and “professional norms that create boundaries between personal and professionally acceptable behaviors.”  She makes cases for why these help employers at the expense of employees, such as a study showing fuzzier times meant unpaid extra hours, flat chains of command meant “employers can punt on” promotions, and Zoom backgrounds allowed us to draw inferences when “you finally get to see where Tyler from quality assurance lives – whether you want to or not.”  This is another group of concerns in flux, built on by “Can Workers Climb the Career Ladder From Outside the Office?” by Corrine Purtill in the March 3rd New York Times, which aired matters such as whether “you can feel people’s energy better when you’re around them” for “assessing someone’s availability,” a controversy about the effectiveness of “virtual water coolers” (which the article did not mention could store and transmit comments), “bonding opportunities like virtual happy hours” with the same problems which may not work across time zones, potentially less real or perceived sex and race discrimination against people not in your field of vision, and reduced numbers of “side conversations,” from which “a lot of decisions are made.” 

Despite any certainty, a strong downward pandemic trend has influenced companies to call employees in on future dates.  That’s what Andrew Keshner found in “Google isn’t the only company requesting workers go back to the office.  Jobs report shows more people are joining the ‘Great Return’” (MarketWatch, March 7th).  Will that mandate hold?  And how will the issues in this post play out?  Only time, and maybe our best projections, will tell.

I will not be posting next week.  Expect the next issue, on a topic to be determined, April 22nd.


Friday, April 1, 2022

Another Solid Employment Report, Showing People Returning to the Labor Force – AJSN Shows Latent Demand Down 400,000 to 16.6 Million

Four weeks ago, I predicted this morning’s Bureau of Labor Statistics Employment Situation Summary would again be especially strong.  Was it?

We added 431,000 net new nonfarm payroll positions, on top of the only estimates I saw (450,000 and 455,000), not in February’s 678,000 class but still about ten times what we need for our current, reduced population increase.  Almost all of the numbers I have been covering improved as well.  Seasonally adjusted and unadjusted unemployment fell 0.2% and 0.3% respectively, to reach 3.6% and 3.8%.  We reached 6.0 million officially jobless people, off 300,000, of whom 787,000, of 101,000 fewer, were on temporary layoff and 1.4 million, also down 300,000, have been out of work for 27 weeks or longer.  The two measures of how common it is for people to be working or unemployed, the labor force participation rate and the employment-population ratio, improved 0.1% and 0.2% and are now at 62.4% and 60.1%.  The laggers were the count of people working part-time for economic reasons, up 100,000 to 4.2 million after last time’s 400,000 gain, and average hourly nonfarm payroll earnings, up 15 cents per hour to $31.73, less than inflation despite February’s loss. 

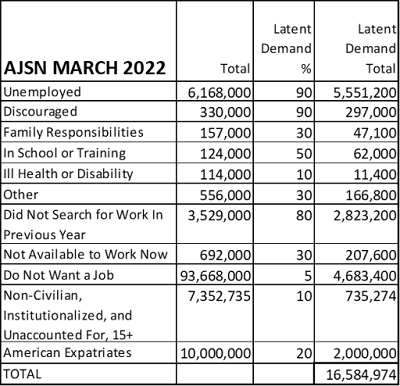
The American Job Shortage Number or AJSN, the measure of how many new positions could be quickly filled if all knew they were easy to get, decreased 402,000, as follows:


 The effect of a lower number of unemployed was significantly offset by more people wanting to work but not looking for it for a year or more.  That was a clear indication that those who in February said they did not want jobs, which decreased over 600,000 in March, came back to the workforce.  The other factors above significantly improved, with their AJSN effects largest for those discouraged and those in school or training.  The share of the AJSN from those officially jobless fell from 35.9% to 33.5%, meaning that essentially two-thirds of new job acceptors would not have been what the Bureau of Labor Statistics considered unemployed.

Compared with a year before, the AJSN has dropped almost 3.9 million, 3.4 million of that from those jobless, half a million from a lower count of people interested in work but not searching for it for at least 12 months, and the other statuses collectively little changed. 

On the pandemic front, the differences in seven-day rolling daily averages between February 15th or 16th and March 16th all showed the dramatic fading of the Omicron variant, with new cases down 75% to 31,216, deaths off 46% to 1,263, people hospitalized dropping 70% to 25,558, and vaccinations, including boosters, 54% lower at 237,025.  There is scant reason, and even less day by day, to think a significant number of people are taking undue risks by working. 

So how good was it… really?  It wasn’t as super-strong as February’s, and the two-month trends of more people counted as employed without the full-time work they want and pay raises not covering increasing prices are causes for concern.  Yet our unemployment rates are only a few tenths of percent higher than they were just before Covid, and much of the effect of higher oil and food prices from the Ukraine war, three weeks old at survey time, is already baked in.  How we do from here will depend on how many of those 600,000-plus new entrants find work.  If they do, April should match or exceed March, but if they don’t, we may more or less break even next time.  For now, though, once again the turtle took a good step forward.

Friday, March 25, 2022

From the Management Side: What’s Been Happening, and What it Means for Workers

While the pandemic has influenced almost everything businesses have been doing in the past year, it has not been the only source of change.  Stories about how companies have been operating, except in ways Covid has driven, have generally been pushed behind the scenes, but reality has marched on.

While slightly mistitled, Nancy Collamer’s August 5th MarketWatch “Four hiring trends you should know about and how to put them to work for you,” while describing mostly long-time truths, still provided a good look at what’s been going on there.  Her first point, that “the hiring process is increasingly automated and virtual,” calls for not only candidate countermeasures but for realizing that some strategies, such as using “referrals to network your way into jobs,” are as important as ever.  It’s nothing new that “interest in remote work remains strong among many workers and employers,” and more and more information is available on how to get such positions.  The third, “diversity and inclusion have moved to the hiring and employment forefront,” could have been written 40 years ago, and, while the same could be said about the fourth, “it’s still not easy for older job seekers,” the latter has been worsened by accelerating working-technology change, meaning that older candidates, in particular, should emphasize their specific software experience areas. 

What skills do hospitality workers now need?  How about conflict resolution?  That they do seems clear from “Restaurants and hotels push back against the uptick in customer tantrums” (Clare Ansberry, Fox Business, September 28th).  Not fresh but still noteworthy, this piece focused on hostile customers who became more common during the pandemic, and are now not tolerated as much.  One restaurant owner found that a simple message on ordinary paper, posted on the front door, saying “BE KIND OR LEAVE,” helped.  And people will try more than that.

On September 29th, Peter Coy of The New York Times asked a good question: “Why are fast food workers signing noncompete agreements?”  Those accords, once reserved for people with high-value proprietary knowledge, have spread disturbingly in the past decade, and, as here, are often used to shackle workers rather than to maintain information security.  Although many such agreements may be invalidated in court, we are not far from nationwide restrictions on when they can be imposed.

We move on to something which management keeps trying, despite no sustained financial success, with “Will Rapid Grocery Delivery Change N.Y.C.?  Look to Berlin,” by Margot Boyer-Dry in the February 11th New York Times.  The currently-attempted model discussed here involves not runs from stores but from “new grocery warehouses, or “hubs,”” which have drawn complaints in that German city for their “noise and congestion,” and may violate zoning rules.  These services have many similarities with Uber and Airbnb, from a lack of profitability to the looming question of whether they could be even nominally successful if they were held to the same regulations as more established enterprises.

“Do Today’s Unions Have a Fighting Chance Against Corporate America?”  Here is another worthwhile query, addressed in article form by E. Tammy Kim on February 17th, also in the Times.  For decades, unions, with their heyday long in the past, have found their growth in representing governmental employees with nonconfrontational management, but have recently gained relevance as intense personal controls, comprehensive monitoring, and daunting production requirements have appeared at the likes of Amazon.  Unions have greatest appeal when employers are abusive or bordering on that – with such behavior on an upswing, they can regain much of the value they had when workers who died on the job were often denied even that day’s pay.  We should not expect labor organizations to resurge in pleasant, safe, reasonably fair workplaces, but when that is threatened, it is appropriate for them to return.

Finally, on the topic of that gargantuan concern, we got “Here Comes the Full Amazonification of Whole Foods” (Cecilia Kang, The New York Times, February 28th).  Amazon bought that grocery retailer “more than four years ago,” and didn’t say much about what they were doing with it for about three of those, but now is pioneering a system where “hundreds of cameras with a god’s eye view of customers” can see exactly what they pick up and walk out with, and bills them later.  The technology is not perfected yet, was only at press time at two locations, and uses “deep-learning software” to improve it, but, if management likes the results, will spread, not only to other Whole Foods stores but to competing chains.  It does, indeed, mean even fewer checkout personnel, but also cost savings that could be passed along.  We’ll see – and that, as well, goes for everything else in this post.

Friday, March 18, 2022

Beyond Inflation and Interest Rate Increases: Where We Are, and Where We Could Go Instead

On Wednesday, the solid Federal Reserve news finally hit.  Per “Fed raises rates and projects six more increases in 2002” (The New York Times, March 16th), the federal funds rate, lower than the prime rate or discount rate, went up 0.25% with more hikes, likely though dependent on how inflation and other factors perform, on the way.  This is a small increase – the Fed has been known to boost or cut rates 2% or more at once – and it shows caution.  Is that a good thing?

The oldest of nine pieces here was published just over a month ago.  In Jeanna Smialek’s February 17th New York Times “Could Wages and Prices Spiral Upward in America?,” the author maintained that “even if wages and prices are both rising now, it is not clear that they are egging each other on yet,” accurate, as the current bout of inflation has specific causes, namely pandemic recovery, workers refusing positions with pre-2021 pay, and a war between two wheat-exporting countries one of which is among the world’s largest oil producers. 

Between political views distorting many people’s assessments of our situation and the emotional effect of high inflation, we have “America’s Very Peculiar Economic Funk,” by Paul Krugman, on March 3rd and also in the Times.  Peculiar, as “if you ask people “How’s the economy doing?” as opposed to “How are you doing?” you get a very different answer.”  As there clearly is a “disconnect,” Krugman held that news sources are “missing a big part of the story if we take negative public views of the economy at face value without pointing out that they’re at odds not just with official statistics but also with self-reported experience.” 

The same author and publication returned with “How the Putin shock might affect the world economy” (March 8th), a good primer on this topic.  Krugman concluded “that it will be bad, but not catastrophic,” with problems centering on grain and fuel as above.  He said the spike in oil prices took him by surprise, in effect a good prediction as it has since greatly receded.

A long-time nuisance for workers may come under deserved pressure, as “Amid rising inflation, many Americans would prefer an increased pay frequency, survey says” (Fox Business, March 9th).  In a recent J.D. Power study, 59% said they were “paid every two weeks,” and of them, 35% (only?) wanted weekly checks instead.  I think those with relatively low income should be paid more often, and with less elapsed time, as it’s fair that they want to spend their earnings sooner.  I urge organizations to improve that.

We read about overall higher prices, but that doesn’t mean they have been going up uniformly.  In fact, there are large differences, as shown in “Where Inflation Is… And Isn’t,” in Yahoo Finance on March 10th.  This chart showed that the “12-month change,” overall 7.9%, had “used vehicles” increasing 41.2%, gasoline 38.0%, hotel rooms 25.2%, rental cars 24.3%, and “transportation” 21.1%, along with “household energy,” airfare, and “new vehicles” each up from 12.4% to 13.3%, and furniture, “food at home,” and “appliances” from 7% to 10% higher, followed by “food at restaurants,” clothing, housing, “personal care,” “pets & pet products,” “recreation, and rent increasing from 4.2% to 6.8%.  This data is important, as it tells us where the problems have and have not been.

Paul Krugman again, in the March 14th New York Times, seemed to have got what he wanted in “How Not to Have a Putin Recession.”  He agreed with small interest rate hikes, but said that “what the Fed should not do, however, is allow itself to be bullied into slamming on the brakes, drastically raising interest rates the way it did in the 1970s” (italics his).  He emphasized oil prices, and our current inflation is more broad-based, but there is indeed more danger in lifting money costs too quickly than too slowly.  A day later we saw “Global Economy Sinks Deeper Into Turmoil as Fed Prepares to Raise Rates” (Ana Swanson and Jeanna Smialek, The New York Times), emphasizing Chinese pandemic-related delays and shutdowns along with the effect of the Russia-Ukraine war on other countries.

Last, issued only hours before the interest-rate announcement, was Peter Coy’s “The Fed could cause a recession, this economist says,” also in the Times.  “The economist David Rosenberg” was concerned that “in trying to steer clear of the Scylla of inflation, the Fed could inadvertently plunge the U.S. economy into the Charybdis of recession.”  That summarizes my view as well.  We’re not going down to 2% inflation this spring, no matter what we rationally do, but we can keep the economy strong as we get it to slowly improve.  That is the best course, and the numbers, if not the people, will confirm that.

Friday, March 11, 2022

Quits, Willingness to Work, and the So-Called Labor Shortage: Where We Stand Now

There’s no lack of employees, any more than there are not enough $10 diamond rings.  More and more businesses are proving it.  That’s what I think.  What about others, and what are the facts?

For one view, “The free market is solving the labor shortage, Republican Rep. James Comer says” (Ben Winck, Business Insider, December 22nd).  Per Comer, “the labor shortage is just the free market setting a new minimum wage,” and “recent wage hikes “probably needed to happen” for adults to earn a livable wage.”  For that reason, many mandated minimum pay levels have become superfluous, which is the healthiest situation we could have.

Soon afterwards we saw The Washington Post’s “Two forces collided to create the most unusual job market in modern American history” (Alyssa Fowers and Andres Van Dam, December 29th).  Those vectors, with similar effects, were “demand for workers came soaring back at a velocity almost never before seen” and “despite companies going all out to hire, millions of workers either retired early or stayed on the sidelines.”  As well as the pandemic fading, the first factor was caused by “the twin fire hoses of cash, one from Congress, one from the Fed.”  The two were enough to reverse a more-than-40-year situation of the supply of candidates exceeding demand.  Given that, it is trivial to see why employees would increasingly leave their jobs, and to understand some of the causes of inflation.

On January 4th in The New York Times, Ben Casselman told us that “More quit jobs than ever, but most turnover is in low-wage work.”  He offered nothing to document the latter, but included a fascinating chart of the “number of people who quit jobs by month,” which showed us that, between the 2009 beginning of the Great Recession and the pandemic’s early 2020 start, this statistic increased, except for small monthly fluctuations, at a remarkably steady pace, about doubling from 1.7 million to 3.5 million.  A graph of job openings looked quite similar, and both, now, are above these trendlines. 

“Will the big worker shortage end this year?”  That’s what Paul Davidson asked in a USA Today article, printed in the Times Herald-Record on January 16th.  The author focused on those who had been taking time off but were running out of money, and noted that the country’s labor force was 2.3 million higher pre-Covid.  As well as fear of the virus, Davidson named the need to care for school-age children not able to go there, “early retirees,” and more than the usual count of “career switchers” and “entrepreneurs,” the second one probably understated, as in more stable times many more own-business efforts were patently adjuncts to larger work earnings.

“Has the Willingness to Work Fallen during the Covid Pandemic?”  This was the title of a National Bureau of Economic Research working paper issued in February.  Authors R. Jason Faberman, Andreas I. Mueller, and Aysegul Sahin claimed that “the labor market is tighter than suggested by the unemployment rate and the adverse labor supply effect of the pandemic is more pronounced than implied by the labor force participation rate.”  True, or at least seems to be, but the American Job Shortage Number (AJSN) results from that time showed that more people, for example 16.3 million in December, would take available positions, if good enough, than there has ever been advertised job openings.

Are we really in “The Age of Anti-Ambition” (Noreen Malone, Yahoo News, February 20th)?  Malone provided views that “almost no one I know likes work very much at the moment,” that “the office is where it shouldn’t be – at home, in our intimate spaces – and all that’s left now is the job itself, naked and alone,” and that “the emotional relationship of American workers to their jobs and to their employers” is not completely accurately describable as “the Great Resignation.”  One group has been especially likely to leave the workforce, as “in early 2021, women’s labor-force participation was at a 33-year low, returning us all the way back to the era when “Working Girl” was revolutionary.”  Add to that lower employee satisfaction in general and the neo-sweatshop positions at Amazon and elsewhere which are sparking the largest private-sector union growth in decades, and you do not get a time for employment’s highlight reel. 

To bring us back to the title, I end with March 9th’s “Employers are still scrambling to fill vacancies, a new U.S. report shows” (Talmon Joseph Smith, The New York Times).  This installment of the Department of Labor’s Job Openings and Labor Turnover Survey (JOLTS) told us that while “job openings dipped to 11.3 million,” and “some 4.3 million people left their jobs voluntarily in January,” down from November’s 4.5 million, those numbers are still historically high.  And, with demand for goods and services extremely strong, until more employers raise their pay and improve working conditions, they will increase if anything.  People are as willing to work than ever – see the AJSN, or ask any company which has raised pay about the most recent 7.9% inflation rate, has kept productivity demands in check, and has allowed other perks, such as remote reporting, when reasonable and justified.  There are plenty of possible candidates – clean the baseboards, put out the food they want, and they will come out of the woodwork.

Friday, March 4, 2022

February’s Employment Numbers Were Hot Ones, Including AJSN Showing Latent Job Demand Off 800,000

We left January’s Bureau of Labor Statistics Employment Situation Summary by calling it a muddled mess, made that way by peaking Omicron cases and annual adjustments.  This morning’s installment made it clear where we are going.

The two marquee statistics, the seasonally adjusted unemployment rate and the gain in nonfarm payroll positions, starred, the first down 0.2% to 3.8% and the second at half again its consensus projection, 678,000.  Most of the others also came out well.  Unadjusted joblessness fell 0.3% to 4.1%, the count of unemployed was off 200,000 to 6.3 million, and there were 71,000 fewer on temporary layoff or 888,000.  The two numbers best showing how many Americans are actually working or one step away, the employment-population ratio and the labor force participation rate, increased 0.2% and 0.1% and are at 59.9% and 62.3%.  There were some laggers – the count of those out of work 27 weeks or longer held at 1.7 million, average private nonfarm payroll earnings lost 5 cents per hour plus the effect of inflation to reach $31.58, and those working part-time for economic reasons, or keeping that level of employment while unsuccessfully seeking full-time propositions, now total 400,000 more or 4.1 million. 

The American Job Shortage Number or AJSN, the one-number statistic showing how many more positions could be quickly filled if all knew they would be as easy to get as a pizza, shed 832,000 as follows:


Almost all of the change was from the count of unemployed, which cut off 382,000, and the number wanting to work but not looking for it during the previous year, now 412,000 fewer.  The other components seemingly only fluctuated.  The share of the AJSN from those officially jobless fell 0.5% to 35.9%, meaning that almost two-thirds of those taking currently unadvertised positions without existing jobs would have other statuses.  Compared with a year before the AJSN has lost 4.2 million, from lower unemployment (3.3 million) and fewer people not looking for a year or more (1.0 million).  The continued large year-over-year improvements show how strong our recovery has been. 

On the pandemic side, the 7-day daily averages from January 16th to February 16th (or the 15th when the 16th was unavailable) showed new cases down 85% to 124,025, deaths up 17% to 2,328, the number hospitalized off 45% to 84,966, and vaccinations down 52% to 516,988.  Mid-January was the absolute peak of the Omicron variant, with hospitalizations and deaths lagging moderate and large intervals, and all of these numbers are still falling.

This time, the jobs data verdict is clear.  February was a robust month, with no hint that we sacrificed health for work and the only real concerns being that possibly-one-time poor payroll earnings result and some secondary statuses hovering in highish territory.  As Covid-19 has lost influence, demand for goods and services has put many more people back to work, and there is every reason that will continue.  Accordingly, the turtle took a big step forward, and is stretching his legs in anticipation of another one.